POLISH COSTA | LAW AND TAXES
183 days isn't everything
When does a Polish citizen living or working in Spain become a Spanish tax resident?
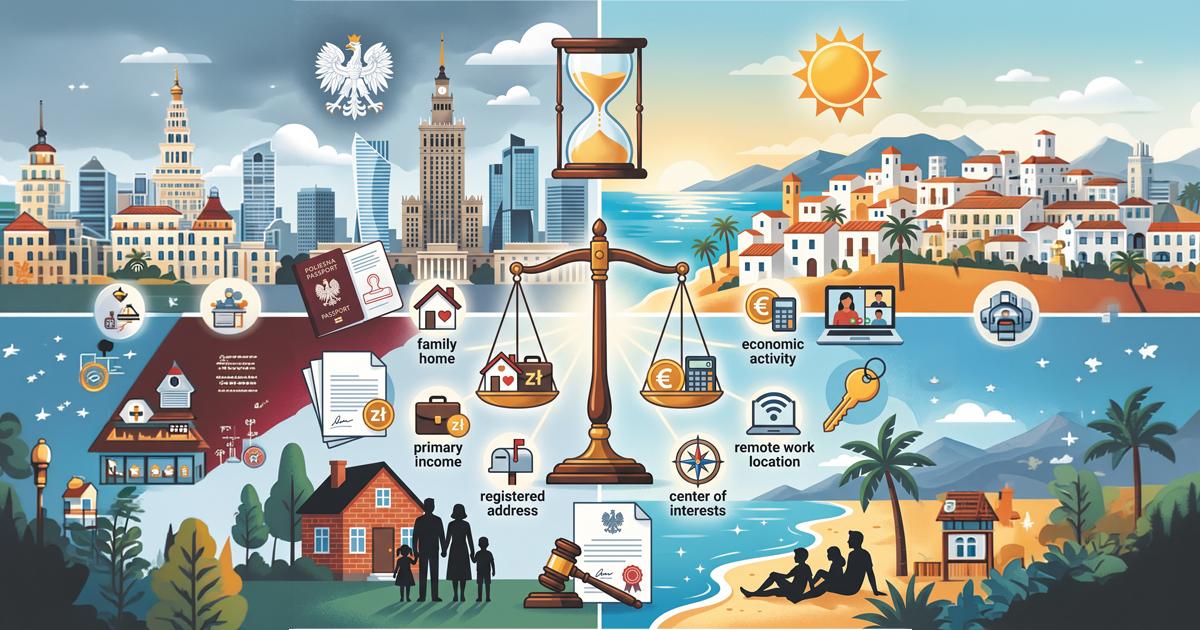
Moving to Spain, working remotely for a Polish company, or running a business in one country while your family lives in another raises a fundamental question: Where should you file your taxes?
The most common answer is: “where I spend 183 days.” This is an important rule, but the number of days alone does not always determine tax residency.
Spain: Three Residency Criteria
Spain may consider an individual to be a tax resident if he or she stays in its territory for more than 183 days in a calendar year. Occasional absences may also be taken into account when calculating the period of stay, unless the taxpayer demonstrates that he or she is a tax resident of another country.
The second criterion is the location of the principal place of business or economic interests. Therefore, it is possible to stay in Spain for fewer than 184 days and still be considered a tax resident there if the business is actually operated, work is performed, or the most significant sources of income are concentrated in Spain.
There is also a presumption related to family. If a spouse with whom the taxpayer is not legally separated, as well as any dependent minor children, reside permanently in Spain, the Spanish tax authority may presume that the taxpayer is also a resident of Spain. This presumption can be rebutted, but specific evidence is required—not merely one’s own belief.
Poland sees it the same way
In Poland, tax residency may result from a stay lasting more than 183 days in a tax year or from having a center of personal or economic interests in Poland, referred to as the “center of vital interests.”
The regulations use the conjunction “or” rather than “and.” This means that it is not necessary to meet both conditions at the same time. A Polish address, family, business, real estate, or primary source of income may still be relevant even if a person spends most of the year abroad.
A change of address, the closure of a business in Poland, or obtaining a Spanish document in the middle of the year does not automatically determine a change in tax residency. The taxpayer’s actual personal and professional circumstances must always be analyzed.
What if both countries consider us a resident?
In such a situation, the Polish-Spanish double taxation treaty applies. The following factors are examined in order: where the person has their permanent residence, where the center of their vital interests is located, in which country they usually reside, and finally, what their citizenship is. In exceptionally complex cases, the matter is resolved by the competent authorities of both countries.
As a general rule, a resident of Spain must report here all income earned worldwide, including wages, rental income, pensions, interest, and other income earned in Poland. However, this does not automatically mean that you have to pay tax twice. An international tax treaty specifies which country has the right to tax a particular type of income and how tax paid abroad is taken into account.
Three Common Mistakes
Mistake 1: “I have a NIE and am registered with the municipal census, so I’m a Spanish tax resident.”
The NIE number, registration, and residence permit are important administrative documents, but they alone do not determine tax residency.
Mistake 2: “I didn’t exceed 183 days, so I’m filing my taxes only in Poland.”
The focus on business, personal, or family interests can lead to a completely different outcome.
Mistake 3: “The employer is based in Poland and pays the salary into a Polish bank account, so the income is solely Polish.”
When working remotely, the location where the work is actually performed is also important.
Two Simple Examples
Anna lives in Alicante from February through November and works from home for a company based in Warsaw. Since she stays there for more than 183 days, she is most likely a tax resident of Spain and should consider whether she is required to report all of her income there.
Piotr spends only 160 days in Spain, but this is where he runs his business, has clients, an apartment, and his family. Staying below the 183-day limit does not guarantee him Polish residency. In his case, the overall circumstances must be examined, and the agreement between Poland and Spain must be applied.
What Should You Do Before Filing Your Tax Return?
It’s a good idea to keep a record of your stays, save your tickets and contracts, determine where you actually performed your work, and gather information about your income and taxes paid in both countries. If in doubt, you can also obtain a tax residency certificate.
The most costly mistake is filing your tax return “as usual,” even though you’ve already moved to another country.
Important: This article is for informational purposes only. Tax residency and the method of taxation should be assessed on a case-by-case basis for a specific year, type of income, and the taxpayer’s personal circumstances.
This article was prepared based, among other sources, on the tax laws in force in Poland and Spain, official information from the Polish Ministry of Finance and the Spanish Agencia Tributaria, and the Polish-Spanish double taxation treaty.
Legal status: August 2026
Contact:
For more information, visit:
I look forward to working with you!
Spanish Lawyer
Professional License No. 1171
API No. 2573
He specializes in providing legal services related to the purchase of real estate in Spain and in offering tax advice to Polish citizens regarding legal and tax matters between Spain and Poland.